Can the Seller Pay My Closing Costs?

Yes, a home seller can contribute toward a buyer’s closing costs. These contributions are commonly called seller concessions, and they can help reduce the amount of money a buyer needs to bring to closing.

However, there are limits on how much a seller can contribute, and those limits can depend on your loan program, down payment, occupancy, and other factors.

Here’s how seller-paid closing costs work and when they might make sense.

What Are Seller Concessions?

Seller concessions are costs that the seller agrees to pay on behalf of the buyer as part of the purchase agreement.

Instead of simply negotiating the price of the home, a buyer may ask the seller to contribute a specific dollar amount or percentage toward eligible closing costs.

Your real estate agent and Loan Officer can help you determine how to structure the request based on your financing and the home you’re purchasing.

What Closing Costs Can a Seller Pay?

Depending on your loan program and transaction, seller concessions may be used toward eligible expenses such as:

  • Certain lender fees
  • Title-related costs
  • Prepaid property taxes
  • Homeowners insurance
  • Discount points
  • Other allowable closing expenses

Not every expense can be covered by a seller, and the rules vary by mortgage program.

That’s why it’s important to coordinate with your Loan Officer before submitting an offer that includes seller concessions.

How Much Can a Seller Contribute Toward Closing Costs?

There isn’t one limit that applies to every mortgage.

Conventional, FHA, VA, USDA, and other loan programs have their own guidelines regarding interested-party contributions or seller concessions. The maximum allowed can also depend on details of the transaction.

Your Loan Officer can calculate the amount that may be permitted for your specific loan.

Do Seller Concessions Lower the Price of the Home?

Not directly.

A seller concession generally reduces the buyer’s eligible closing expenses rather than reducing the home’s purchase price.

For example, negotiating a lower purchase price and negotiating money toward closing costs can have very different effects on how much cash you’ll need at closing.

For a buyer who wants to preserve savings, a seller contribution toward closing costs may sometimes be more helpful than a similar reduction in the purchase price.

Can Seller Concessions Be Used to Lower My Interest Rate?

In some situations, seller concessions may be used to pay discount points or fund an eligible interest-rate buydown.

That could help reduce the buyer’s mortgage payment, depending on how the loan is structured.

There are specific rules and limitations, so your Loan Officer should review the numbers before you decide how to use a seller contribution.

Do I Have to Ask the Seller to Pay Closing Costs?

Yes. Seller concessions are typically negotiated as part of the purchase agreement and aren’t guaranteed.

Whether a seller is willing to contribute can depend on the property, the strength of your offer, competing offers, and current market conditions.

Your real estate agent can help you determine how a request for seller concessions fits into your overall offer strategy.

Are Seller Concessions the Same as Down Payment Assistance?

No.

Seller concessions come from the seller and are generally used toward eligible costs associated with the transaction.

Down payment assistance programs are separate programs that may provide eligible buyers with assistance toward a down payment, closing costs, or both, depending on the program.

In some situations, buyers may be able to take advantage of more than one source of assistance, subject to loan and program guidelines.

Are Seller-Paid Closing Costs Worth Asking For?

They can be.

Seller concessions may be particularly helpful for buyers who have enough money for their down payment but want to keep more of their savings available after purchasing the home.

But every transaction is different. Sometimes negotiating the purchase price is more important. In other situations, asking for closing-cost assistance could provide a greater immediate benefit.

Understanding the numbers before writing the offer can help you make that decision.

The Bottom Line: Talk to Your Loan Officer Before Making an Offer

Yes, sellers can help pay a buyer’s closing costs, but the amount and eligible expenses depend on the mortgage program and transaction.

That’s why your financing strategy shouldn’t begin after your offer is accepted.

At Michigan Mortgage, we’ll help you understand your estimated closing costs, determine how much a seller may be allowed to contribute, and show you how different scenarios could affect the money you’ll need at closing.

Thinking about buying a home in Michigan? Talk with a Michigan Mortgage Loan Officer before you make an offer. We’ll help you understand your numbers and your options.
Can I Buy a House Before I Sell My Current Home?

You found the house you want to buy, but there’s one problem: you still own your current home.

Do you have to sell first?

Not necessarily. It may be possible to buy your next home before selling your current one, depending on your finances, available equity, and the mortgage options you qualify for.

For homeowners who are ready to move, understanding your options before listing your current home can make the transition much easier.

Can I Qualify for a New Mortgage Before My Current Home Sells?

Possibly.

One of the first things your Loan Officer will look at is whether you can qualify while you still have a mortgage payment on your current home.

Your income, existing debts, available assets, credit, and the amount of equity you have in your current home can all play a role.

If carrying both homes temporarily isn’t an option, that doesn’t automatically mean you have to sell first. There may be other strategies worth exploring.

What Is a Bridge Loan?

A bridge loan is a short-term financing option designed to help homeowners “bridge” the gap between their current home and their next one.

Depending on the program and your situation, a bridge loan may allow you to access some of the equity in your current home before it sells.

Those funds could potentially be used toward the purchase of your next home, allowing you to move forward without waiting for your current sale to close.

Once your existing home sells, the bridge loan is typically paid off according to the terms of the loan.

Why Would Someone Buy Before Selling?

For many homeowners, it’s about making the move easier.

Buying first may give you more time to find the right home instead of feeling pressured to purchase something simply because your current home sold.

It can also help you avoid trying to coordinate two closings on the same day, moving everything at once, or finding temporary housing between homes.

In a competitive housing market, it may also allow you to make an offer without a home-sale contingency, depending on your financing and situation.

What Are the Risks of Buying First?

Buying before selling isn’t right for everyone.

For a period of time, you could be responsible for expenses associated with both properties. You’ll also need to consider what happens if your current home takes longer to sell or sells for less than anticipated.

That’s why it’s important to understand the numbers before making an offer on your next home.

Your Loan Officer can help you look at different scenarios so you know what the transition could realistically look like.

Should I Sell My House First or Buy First?

There’s no universal right answer.

Selling first may make sense if you need the proceeds from your current home to purchase the next one or want to minimize financial risk.

Buying first may make sense if you have sufficient income, savings, or home equity and want more flexibility when searching for your next home.

The best strategy depends on your finances, your local housing market, and what matters most to you during the move.

Start With the Financing Before You Start House Hunting

If you’re thinking about selling and buying at the same time, don’t wait until you’ve found your next house to figure out the financing.

Michigan Mortgage can help you understand how much equity you have, what you may qualify for, and whether options like a bridge loan could help you make the move.

There may be more than one way to get from your current home to your next one. Let’s find the one that makes the most sense for you.

Should I Use a Local Mortgage Lender or an Online Lender?

When you’re buying a home, you’ll have no shortage of mortgage options. From national online lenders to local mortgage companies, it can be difficult to know which is the right choice.

While every buyer’s needs are different, there are several advantages to working with a local mortgage lender.

Local Market Knowledge

A local lender understands the housing market where you’re buying.

They know the neighborhoods, local real estate professionals, and common challenges that can arise during a transaction. That local expertise often helps keep the process moving smoothly.

Personalized Service

With an online lender, you may speak with a different person every time you call.

With a local lender, you’ll typically work with the same loan officer from pre-approval through closing. That means you’ll have someone who knows your situation and can answer your questions along the way.

Better Communication

Buying a home involves several people working together, including your real estate agent, title company, and lender.

Local lenders often have established relationships with professionals in the community, making communication faster and more efficient.

Every Loan Is Different

Online lenders often rely on standardized processes.

Local lenders take the time to understand your goals and recommend loan options that fit your unique financial situation. Whether you’re a first-time homebuyer, purchasing your forever home, or refinancing, personalized guidance can make a significant difference.

Competitive Loan Options

Many buyers assume online lenders always offer the lowest rates.

The truth is, interest rates, loan programs, and closing costs vary based on many factors. The best way to compare your options is to speak with a trusted loan officer who can explain the complete picture, not just one number.

The Bottom Line

A mortgage is one of the biggest financial decisions you’ll ever make.

Choosing a lender isn’t just about finding a loan. It’s about finding a trusted partner who will educate you, communicate with you, and guide you through the process with confidence.

At Michigan Mortgage, we’re proud to serve homebuyers across Michigan with personalized service, local expertise, and a commitment to making the mortgage process as smooth as possible.

If you’re thinking about buying a home, we’d love the opportunity to earn your trust and help you achieve your homeownership goals.

Can I Buy a House With Student Loan Debt?

If you have student loans, you may be wondering if homeownership is still within reach.

The answer is yes. In fact, many homeowners are successfully buying homes while paying off student loans.

Having student loan debt doesn’t automatically prevent you from qualifying for a mortgage. The key is understanding how lenders evaluate your overall financial picture.

How Do Student Loans Affect a Mortgage?

When you apply for a mortgage, lenders look at your debt-to-income ratio (DTI). This compares your monthly debt payments to your monthly income.

Student loan payments are included in that calculation, along with other debts like:

  • Car loans
  • Credit cards
  • Personal loans
  • Existing mortgages

Your student loans are just one piece of the equation.

Does the Amount I Owe Matter?

Surprisingly, the balance itself is often less important than your monthly payment.

For example, someone with a larger student loan balance and a manageable monthly payment may qualify more easily than someone with a smaller balance but significant monthly debt obligations elsewhere.

Every situation is unique.

What If My Loans Are Deferred?

Depending on the loan program, deferred student loans may still need to be considered when calculating your qualifying ratios.

Your loan officer will explain how your specific loan program handles deferred or income-based repayment plans.

Don’t Assume You Won’t Qualify

One of the biggest mistakes potential buyers make is ruling themselves out before speaking with a lender.

We’ve worked with teachers, nurses, doctors, recent graduates, and countless other professionals who believed their student loans would keep them from buying a home. Many were pleasantly surprised to learn they had more options than they expected.

The Bottom Line

Student loan debt doesn’t have to stand between you and homeownership.

At Michigan Mortgage, we’ll review your financial picture, explain your options, and help you determine what loan programs may work best for your situation.

If you’ve been waiting because of student loans, let’s have a conversation. You may be closer to buying a home than you think.

How Long Does It Take to Get a Mortgage?

If you’re planning to buy a home, you’ve probably wondered, “How long does it take to get a mortgage?”

The short answer is: Most home loans close in about 30 days, but every situation is different.

The timeline depends on several factors, including how quickly documents are provided, the type of loan, the appraisal, and the title process. Understanding what to expect can help you prepare and avoid unnecessary delays.

Step 1: Get Pre-Approved

The mortgage process begins with a pre-approval. During this step, your loan officer reviews your income, assets, credit, and employment to determine how much you may qualify to borrow.

If you have your documents ready, many buyers can receive a pre-approval in as little as a day.

Step 2: Find a Home

Once you’re pre-approved, you’ll work with your real estate agent to find the right home.

This part of the process varies from buyer to buyer. Some find the perfect home in a weekend, while others spend several weeks or months searching.

Step 3: Submit Your Loan Application

After your offer is accepted, your loan application is finalized and moves into processing.

During this stage, your mortgage team will:

  • Verify your financial information
  • Order the appraisal
  • Coordinate with the title company
  • Review all required documentation

You may be asked to provide additional paperwork along the way. Responding quickly helps keep your closing on schedule.

Step 4: Underwriting

The underwriter reviews your loan file to ensure it meets lending guidelines.

Sometimes they’ll request additional information or documentation before issuing final approval. This is completely normal and happens with many mortgage transactions.

Your loan officer will guide you through any conditions that need to be satisfied.

Step 5: Closing Day

Once your loan receives final approval and all closing documents are prepared, you’ll schedule your closing.

You’ll sign the final paperwork, receive your keys, and officially become a homeowner.

What Can Delay a Mortgage?

While most transactions move smoothly, a few things can slow the process down, including:

  • Missing or incomplete documentation
  • Large bank deposits that need explanation
  • Employment changes during the loan process
  • Delays with the appraisal or title work
  • Opening new credit accounts before closing

The best way to avoid delays is to stay in close communication with your loan officer and respond promptly to any requests.

Can the Process Be Faster?

Yes.

When buyers are pre-approved before they begin shopping and provide requested documents quickly, many loans move efficiently from application to closing.

Working with an experienced local lender can also help keep communication clear and the process on track.

The Bottom Line

Buying a home is exciting, and knowing what to expect can make the process feel much less overwhelming.

At Michigan Mortgage, we’re committed to keeping you informed every step of the way. From pre-approval to closing day, our goal is to make your mortgage experience as smooth and stress-free as possible.

If you’re thinking about buying a home, reach out to Michigan Mortgage today. We’d love to help you get started.

How Much Money Do I Need to Buy a House?

One of the biggest myths about buying a home is that you need a huge savings account before you can even think about becoming a homeowner.

The truth? Many buyers qualify with much less money than they expect.

So, how much money do you actually need to buy a house?

The answer depends on several factors, including the type of loan you choose, the price of the home, and whether you qualify for down payment assistance. Let’s break it down.

Do I Need 20% Down?

No.

While a 20% down payment can help you avoid private mortgage insurance (PMI), it’s far from a requirement.

Many buyers purchase homes with much smaller down payments, and some loan programs even offer zero down for qualified borrowers.

The best loan option depends on your financial situation, not a one-size-fits-all rule.

What Costs Should I Expect?

Buying a home involves more than just the down payment. You’ll also want to plan for:

Down Payment

Your down payment is the amount you contribute toward the purchase price. Depending on the loan program, this could range from zero down to a larger percentage if you choose.

Closing Costs

Closing costs are fees associated with finalizing your mortgage and purchasing your home. They may include items such as:

  • Loan fees
  • Title services
  • Appraisal
  • Recording fees
  • Prepaid taxes and homeowners insurance

Your loan officer will provide an estimate of these costs early in the process so there are no surprises.

Earnest Money Deposit

When you make an offer on a home, you may include an earnest money deposit. This shows the seller you’re serious about buying the home.

In most cases, those funds are credited toward your purchase at closing.

Can I Get Help With My Down Payment?

Yes.

Many buyers, especially first-time homebuyers, may qualify for down payment assistance programs.

Depending on the program and your eligibility, assistance may help cover part of your down payment or closing costs, making homeownership more affordable.

Many buyers are surprised to learn these programs exist, which is why it’s important to speak with a knowledgeable loan officer before assuming you need years to save.

Should I Wait Until I’ve Saved More?

Not necessarily.

Waiting longer may allow you to save a larger down payment, but home prices and interest rates can also change over time.

The best time to buy depends on your overall financial picture, your monthly budget, and your long-term goals.

A conversation with a mortgage professional can help you compare your options and decide what makes the most sense for you.

The Bottom Line

You don’t have to guess how much money you’ll need to buy a home.

At Michigan Mortgage, we’ll help you understand your options, explain every cost, and determine whether there are loan programs or down payment assistance opportunities available to you.

Whether you’re planning to buy next month or next year, we’re here to help you create a plan that fits your budget and your goals.

Contact Michigan Mortgage today to find out how close you are to homeownership.

Should I Get Pre-Approved Before Looking at Homes?

Scrolling through home listings is exciting. It’s easy to imagine yourself in a new kitchen, relaxing on the back patio, or hosting family holidays in a space that’s finally your own.

But before you schedule showings or fall in love with a home online, there’s one important step that can save you time, reduce stress, and make your offer stronger: getting pre-approved for a mortgage.

What Is a Mortgage Pre-Approval?

A mortgage pre-approval is a review of your finances by a lender to determine how much you may be able to borrow.

During the process, your loan officer will review items like:

  • Your income
  • Employment history
  • Credit
  • Assets
  • Monthly debts

Once completed, you’ll receive a pre-approval letter showing the price range you’re qualified to purchase.

Why Get Pre-Approved First?

Many buyers want to start house hunting right away, but getting pre-approved first offers several advantages.

You’ll Know Your Budget

Online mortgage calculators can only estimate what you might qualify for. A pre-approval gives you a much clearer picture based on your actual financial situation.

Knowing your budget helps you focus on homes that fit comfortably within your price range.

Your Offer Becomes Stronger

In today’s market, sellers want confidence that a buyer can complete the purchase.

Including a pre-approval letter with your offer shows you’ve already taken an important step and are serious about buying. In competitive situations, that can make a meaningful difference.

You’ll Avoid Disappointment

Imagine finding the perfect home only to discover it’s outside your budget.

Getting pre-approved first helps prevent heartbreak by giving you realistic expectations before you start touring homes.

You’ll Have Time to Address Any Issues

Sometimes the pre-approval process uncovers opportunities to strengthen your application, whether that’s paying down a credit card, documenting additional income, or choosing a different loan program.

It’s much better to discover those items before you’re under contract than while you’re racing toward a closing date.

Does Getting Pre-Approved Mean You’re Committed?

Not at all.

A pre-approval doesn’t obligate you to buy a home or move forward with a loan. It simply gives you the information you need to shop with confidence.

Think of it as preparing before making one of the biggest financial decisions of your life.

The Best Time to Start Is Before You Think You’re Ready

Many buyers wait until they believe everything is perfect before talking with a lender.

The truth is, starting the conversation early gives you more options. Even if you’re several months away from buying, a loan officer can help you understand what steps to take now to put yourself in the best position when the time comes.

Ready to Take the First Step?

At Michigan Mortgage, we believe buying a home should feel exciting, not overwhelming.

Whether you’re planning to buy next month or next year, we’ll help you understand your options, answer your questions, and create a plan that’s right for you.

Getting pre-approved is quick, straightforward, and one of the smartest first steps you can take toward homeownership.

What Credit Score Do I Need to Buy a House?

One of the biggest misconceptions about buying a home is that you need perfect credit to qualify for a mortgage.

The reality? Many homebuyers are surprised to learn they may be closer to qualifying than they think.

While your credit score is an important factor in the mortgage process, it’s only one piece of the puzzle. Understanding how credit impacts your home loan can help you prepare and move forward with confidence.

Why Does Your Credit Score Matter?

Your credit score helps lenders evaluate how you’ve managed debt in the past. It gives insight into your payment history, credit usage, and overall financial habits.

A higher credit score can help you:

  • Qualify for more loan programs
  • Access lower interest rates
  • Potentially reduce your monthly payment
  • Improve your overall borrowing power

However, a lower credit score doesn’t automatically mean homeownership is out of reach.

Different Loan Programs Have Different Requirements

There is no single credit score requirement for every mortgage.

Depending on the loan program, buyers may qualify with scores that are lower than they expect. That’s why it’s important not to assume you won’t qualify based solely on something you’ve read online.

Every borrower’s situation is unique, and different loan options may be available depending on factors such as:

  • Income
  • Employment history
  • Debt levels
  • Down payment amount
  • Overall financial profile

Your Credit Score Isn’t the Whole Story

Many buyers focus exclusively on their credit score, but lenders review much more than that.

They also look at:

  • Your debt-to-income ratio
  • Employment stability
  • Available assets
  • Payment history
  • Down payment funds

It’s possible for someone with a lower credit score and strong financial habits to be in a better position than someone with a higher score and significant debt.

Simple Ways to Improve Your Credit

If you’re planning to buy a home in the future, there are several steps that may help strengthen your credit profile:

Make Payments on Time

Your payment history is one of the most important factors affecting your score.

Keep Credit Card Balances Low

High credit utilization can negatively impact your score, even if you’re making payments on time.

Avoid Opening New Accounts

Opening multiple accounts in a short period can temporarily lower your score.

Review Your Credit Report

Mistakes happen. Reviewing your report regularly can help identify errors that may be affecting your score.

Don’t Disqualify Yourself

One of the biggest mistakes potential buyers make is assuming they aren’t ready to buy without ever speaking to a lender.

We’ve helped many buyers who thought their credit wasn’t good enough, only to discover they had options available today or a clear plan to get there.

Let’s Create a Plan

Whether you’re ready to buy now or simply want to understand your options, Michigan Mortgage can help.

We’ll review your situation, answer your questions, and provide a roadmap to homeownership based on your goals.

You may be closer to buying a home than you think.

What NOT to Do After You Apply for a Mortgage

Getting pre-approved for a mortgage is exciting. It means you’re one step closer to buying a home. But many buyers don’t realize that what happens after you apply can be just as important as getting approved in the first place.

During the mortgage process, lenders continue reviewing your financial information all the way up to closing day. Even small financial changes can impact your loan approval.

Here are some of the biggest mistakes to avoid after applying for a mortgage.

Don’t Open New Credit Cards or Loans

It can be tempting to finance new furniture, appliances, or a vehicle once you start planning for your new home. But opening new lines of credit can affect your credit score and increase your debt-to-income ratio.

Even a small monthly payment can change your qualifying numbers.

It’s best to wait until after closing before making major purchases or applying for additional credit.

Don’t Make Large Deposits Without Documentation

Lenders are required to verify where your funds are coming from. Large deposits into your bank account can create additional paperwork and delays if they can’t be properly sourced.

If you receive gift funds from family or transfer money between accounts, communicate with your loan officer first so they can guide you on the best way to handle it.

Don’t Change Jobs Without Talking to Your Loan Officer

A new job opportunity may sound exciting, but changing employment during the mortgage process can impact your approval timeline.

In some cases, it may not cause an issue at all. In others, it could require additional documentation or affect loan qualification.

Before making any employment changes, it’s important to have a conversation with your lender first.

Don’t Miss Payments

Continue making all of your current payments on time throughout the mortgage process.

A late payment on a credit card, car loan, or other account can lower your credit score and potentially affect your loan approval.

Consistency matters.

Don’t Assume You’re Fully Approved Until Closing

Many buyers think they’re “done” once they receive pre-approval or even conditional approval. But lenders typically complete final checks before closing, including:

  • Credit refreshes
  • Employment verification
  • Asset verification

That’s why staying financially consistent is so important until the keys are officially in your hands.

Communication Is Key

The mortgage process does not have to be stressful, especially when you have the right team guiding you along the way.

If you’re unsure whether a financial decision could impact your loan, ask your loan officer first. A quick conversation can help avoid unnecessary delays or surprises.

We’re Here to Help

At Michigan Mortgage, our goal is to make the mortgage process smooth, simple, and stress-free.

We’ll help guide you every step of the way so you can move into your new home with confidence.

Have questions about getting pre-approved or preparing to buy? Reach out to our team today.

Annabelle Dkystra chosen as 2026 Service Scholarship Winner

In 2020 Michigan Mortgage introduced the Service Scholarship with the goal of recognizing High School Seniors who shared the dreams of pursuing a career in service.

Careers in service include:

  • Military
  • Teachers & Educators
  • Government & Politics
  • Police
  • Firefighters
  • First Responders
  • Doctors & Nurses

For 2026, we received dozens of applicants and reviewed each one closely. We learned about each students’ goals and aspirations, community service they completed, impacts they made in West Michigan, and how they plan to give back to those that need it most.

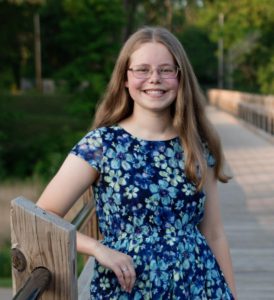
After much consideration, Michigan Mortgage is pleased to announce Annabelle Dkystra, a 2026 Western Michigan Christian graduate, as a winner of this year’s Michigan Mortgage Service Scholarship.
She said the following in her application.

“To me, service means intentionally caring for the people around me and being willing to help wherever there is a need. I believe service is about coming alongside others with compassion, patience, and a genuine desire to support them.”

Annabelle is headed to Spring Arbor University in the fall to pursue a degree in Secondary Math Education.

“Education is important to me because helping others has always been something I’ve loved, especially in school,” she said. “Growing up with my mom as a teacher inspired me from a young age, and I’ve always enjoyed helping classmates and younger peers understand concepts and gain confidence in themselves. ”

“I believe teaching is a meaningful way to serve the community, as educators often become trusted mentors and sources of guidance for students,” she continued. “By creating a supportive and encouraging classroom environment, I hope to make a lasting, positive impact on the lives of my students and the community as a whole.”

Why Annabelle? She is a dedicated and thoughtful student who genuinely cares about learning. She works hard not just to complete her assignments, but to fully understand them, and she isn’t afraid to ask questions to get there. What truly makes her stand out, though, is her kindness and willingness to help her classmates.

We were told that she is patient, compassionate and brings both diligence and heart to everything she does. She truly cares about making this world a better place.

“I am very grateful for the support as I take this next step toward achieving my goal of becoming a teacher,” she said.

Congratulations, Annabelle! We can’t wait to watch you change the world!

Michigan Mortgage is a division of Mortgage One, Inc. NMLS#129386
Secret Link